Sunday, March 22, 2015

Chiseling on a road

There are a couple of ways to chisel your way to building a road.

Sydney, and much of urban Australia, paid through the nose for toll roads to make the daily grind of commuters more convenient, as Guambat has noted on more than one occasion.

My how that effort is just so unspeakably mercenary compared to the work of one man, Dashrath Manjhi.
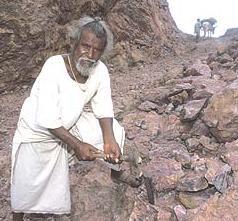
Manjhi started off his extraordinary task in 1960, after his wife was injured while trekking up the side of one of the rocky footpaths leading from his remote village in India to take food to him where he was gathering wood. To reach the nearest hospital, he had to travel around the mountains, some 70 kilometers.

His quest to break a path through a small mountain to benefit the entire village is now legendary because he carved an entire road with hand tools, working for 22 years.

He sold the family’s three goats to buy the hammer and chisels and worked every day on the project to make it a successful. After plowing fields for others in the morning, he would work on his road all evening and throughout the night.

Armed with only a sledge hammer, chisel, and crowbar, he single-handedly began carving a road through the 300-foot mountain that isolated his village from the nearest town.

With sides 25 feet high, the road is 30 feet wide and 360 feet in length. Because of his singular dedication, the distance to public services was reduced from 70km to just one.


Read and see more of this remarkable man who selflessly chiseled a road and broke a mountain to provide a lasting benefit to his community here.

And read more of the remarkable men and women who selfishly chiseled their way to a road and broke a lot of  people to provide questionable benefits to their community here.

Labels: , , ,

Friday, May 11, 2012

I'm so sorry

I'm sorry, so sorry
That I was such a fool

JPMorgan reveals $2B trading loss,
CEO Dimon apologizes


I didn't know
Love could be so cruel

the errors are embarrassing

Oh, oh, oh, oh
Uh-oh
Oh, yes

egg on our face

You tell me mistakes
Are part of being young

bout a trader, nicknamed the ‘London Whale'

But that don't right
The wrong that's been done

It could cost us

[Spoken:]
(I'm sorry) I'm sorry
(So sorry) So sorry

one of the kings of Wall Street

Please accept my apology
But love is blind

some people may lose their jobs

And I was too blind to see

a complete tempest in a teapot

Oh, oh, oh, oh
Uh-oh
Oh, yes
he still believes in his arguments
against the Volcker rule
But that don't right
The wrong that's been done


Apologies to Brenda Lee
I'm so sorry
Oh, oh, oh, oh
Uh-oh
Oh, yes

Labels: ,

Wednesday, January 25, 2012

Bitter late if ever

The following story is truly gobsmacking in its dilettantism.

Seven years ago Guambat had a go at the so-called PPP financing scheme for major infrastructure. (Look here.) As many foresaw, it ended in disaster for investors, planners, citizens and government.

Now, at last, the finance overseers, who overlooked this at the time, are talking about getting around to bolting the door.

Ai adai.

Big projects get tough new scrutiny
THE corporate watchdog has cracked down on fund-raising in the infrastructure sector to prevent a repeat of debacles such as BrisConnections and Sydney's Cross City Tunnel.

Investors in infrastructure lost billions in a series of collapses and near-collapses after the global financial crisis.

Under the new rules, which have met with stiff opposition in the industry, infrastructure companies will have to either give investors far more information about their management, finances, modelling and forecasts, or explain why not.

Read more: http://www.smh.com.au/business/big-projects-get-tough-new-scrutiny-20120124-1qfob.html#ixzz1kOw5ommr

Talk. Nothing more. The horse has bolted. And is still running free. We need a right proper stockman to handle the brumbies, but ASIC ain't no Man From Snowy River.

Labels: , ,

Wednesday, July 06, 2011

Of banks and bailing wire

File this under financial wizardry, of the sovereign kind, with a European flair.

Is the European Union bailing out Greece?

Euro zone approves 12bn euros bailout for Greece
Euro zone finance ministers have approved a 12 billion euro installment of Greece’s bailout, but signaled that the nation must expect significant losses of sovereignty and jobs.

Ministers in the Euro-group gave the go-ahead for the fifth tranche of Greece’s 110-billion-euro financial rescue agreed last year, and said details of a second aid package for Athens would be finalized by mid-September.

But within hours of Saturday’s decision, Eurogroup chairman, Jean-Claude Juncker, warned Greeks that help from the EU and Inter-national Monetary Fund (IMF) would have unpleasant consequences.

Sounds a bit like it, but it depends, to some significant extent, on how you define "bail-out". And definition is everything in A Europe of judges.

EU: No-bailout rule III
In the Treaty establishing a Constitution for Europe the provisions on economic policy were located in Part III ‘The policies and functioning of the Union’, Title III ‘Internal policies and action’, Chapter II ‘Economic and monetary policy’, Section 1 ‘Economic policy’.

The ‘no-bailout’ clause is found in Article III-183, OJ 16.12.2004 C 310/78:

Article III-183 Constitution

1. The Union shall not be liable for or assume the commitments of central governments, regional, local or other public authorities, other bodies governed by public law, or public undertakings of any Member State, without prejudice to mutual financial guarantees for the joint execution of a specific project.
'No Bailout' Clause? The EU's Greek Rescue Problems
European Policy Centre CEO Hans Martens is referring to the 'No Bailout' clause in the European treaty. Article 103 says that: the Union shall not be liable for or assume the commitments of central governments.

This article was specially written to leave ensure no EU country would be saved by the EU if it doesn't respect the Union's economic rules. And that's precisely the case in Greece.

On the other hand, if the European leaders are really willing to aid Greece, they can simply ignore the first clause and go with article 122, which states: when a member-state 'is in difficulties or is seriously threatened with severe difficulties caused by natural disasters or exceptional occurrences beyond its control, the Council [of national governments], on a proposal from the Commission, may grant, under certain conditions, Union financial assistance to the member-state concerned.

ECB's Stark rejects EU guarantees for Greek debt
A senior European Central Bank policymaker rejected the idea of a Greek debt solution involving EU guarantees on Wednesday, and said Greece would face economic collapse if it restructured its debt.

Asked about a scenario under which banks exchanged their Greek bonds for new paper backed by guarantees from EU states - an approach that would be similar to that used in Latin America in the 1980s - Juergen Stark said: "This instrument is disqualified."

"It would break the ban on support - the no bail-out clause in article 125 of the EU Treaty," Stark, a member of the ECB's Executive Board, told German newspaper Die Zeit in an interview.

The U.S.A. and Europe Are Reaching the End of the Line
Because of the sins of the € Commission, the European Central Bank (ECB), and the governments, which have repeatedly violated the no-bailout clause of the European Union's Maastricht Treaty with their so-called rescue packages, plus the ECB's acquisition of toxic government bonds, a situation has now arisen in which the ECB could become technically bankrupt overnight.

UPDATE 1-Finland demands bailout guarantees, bank participation
Finland's new finance minister said on Tuesday that the Nordic country will demand guarantees if it participates in any new euro area bailouts and that it wants private investors to bear more of the burden.

"We want to limit Finland's responsibilities. The new government has taken a tougher stance than the previous government regarding crisis countries' aid packages," Jutta Urpilainen said in a television interview with public broadcaster YLE.

She said the guarantees could be in the form of shares in a company managing the debt-laden state's property.

UPDATE 1-S&P warning adds default threat to Greece's bailout woes
Greece would likely be in default if it follows a debt rollover plan pushed by French banks, S&P warned on Monday, deepening the pain of a bailout that one European official said will cost Athens sovereignty and jobs.

Derivatives industry body ISDA said before the French proposal was released in late June that a voluntary agreement to roll over Greek debt would "typically" not trigger payments on credit default swaps.

European politicians and bankers had expressed confidence last week that the French proposal would not trigger a default, but ratings agency Standard & Poor's said it would involve losses to debt holders, most likely earning Greece a "selective default" rating. S&P cut Greece's sovereign rating to "CCC" last month, from "B", on a view that any restructuring of the country's massive debt load would count as an effective default.

Greece crisis: German lenders 'join rollover plan'
German lenders and insurers have agreed to participate in a plan to continue lending to Greece, according to German finance minister Wolfgang Schaeuble.

He was speaking after a private meeting of the country's main banks.

Mr Schaeuble said German institutions would contribute 3.2bn euros ($4.6bn, £2.9bn) to the plan, details of which have yet to be finalised.

It comes after French banks agreed to relend about half of Greek debts they own coming due by 2014.

Deutsche, Germany's biggest lender, was expected to contribute less than 1bn euros to the plan, according to reports in Germany.

Commerzbank , Germany's second-biggest lender, is likely to contribute far less than 1bn euros, the reports said.

The French plan is designed to make Greece's debtload more manageable in a way that would not be deemed a formal default.

If the deal is classified as a default by ratings agencies or credit derivatives traders, it could force European banks to recognise billions of euros in losses in Greek debts that they currently hold, putting their own solvency at risk.

A couple of years ago, ECB warns Germany against EU bail-out
The European Central Bank gave a thinly veiled warning to the German government on Friday not to violate the European Union’s “no bail-out” clause, which prevents members of the eurozone from supporting other members that are facing rising public debt.

Jürgen Stark, ECB executive board member, told Spiegel magazine in an interview released on Friday that the clause was an “important basis for the functioning of the monetary union”.

The warning follows reports that Germany was considering ways to help members of the eurozone that are facing fast-rising refinancing costs as investor fears rise about deteriorating public finances.

The “no bail-out” clause of the EU treaties prohibits countries from becoming “liable for” or assuming “the commitments” of other governments and is regarded by the ECB as an important weapon for ensuring fiscal discipline.

Asked about the issue on Friday, Frank-Walter Steinmeier, foreign minister, said; “A process is now starting to consider to what extent support via the eurozone and the economically strong countries of the eurozone can happen.”

Fast forward back to the present, German court considers challenge to EU bail-outs
Germany's Constitutional Court is hearing a challenge to the country's participation in bail-outs of Greece, the Republic of Ireland and Portugal.

A Berlin professor argues that the process violates constitutional provisions and should be blocked.

Germany's finance minister rejected the claim, saying all rescue packages had been made on solid legal ground. Experts say the court is unlikely to block Germany's participation in the eurozone bail-outs altogether.

German court hears case against bail-outs
The signs are still that the case is unlikely to cause serious problems for Berlin – the court last year declined to issue an injunction to prevent financial transfers to Greece. Judges signalled they were sceptical that an infringement of EU law would fall under their competence. However, as one government official remarked: “The court is always good for surprises.”

A decision is expected in September or October.

Labels: , ,

Friday, July 01, 2011

It's a WIN-when? situation

What is the corporate tax rate in the USA? Doesn't matter if there is nothing taxed, does it? It's a European holiday for free.

If companies are allowed, indeed encouraged by certain "transfer pricing" regimes or other structured loopholes mechanisms, to park profits overseas and then every few years simply bring them back "home" to "repair" balance sheets, "create jobs" or just about any other euphemism you can choose for "avoid tax payments", companies get away with tax avoidance scott-free regardless of the ersatz tax rate.

Indeed, such "repatriation" schemes, from the stance of global companies, is just one more "transfer pricing" get out of tax jail free card.

Yeah, the US corporate tax rate may or may not be competitive/fair/productive or whatever, but it really doesn't matter if it is never imposed, or if imposed, done so on only a very small portion of profits. So, yeah, they may be taxed at a higher rate, but when if not ever?

Back in 2004 many of these global companies, claiming a tax "home" in the USA, transferred billions of dollars from other tax havens back to the US tax haven is a scheme called "repatriation", but it was like repatriating draft dodgers, only here it was repatriating tax dodgers.

They did it under a cynical scheme, sold easily to the US Congress, called the "Homeland Investment Act of 2004".

Same guys, same scheme is being reheated in the Congressional kitchen under the new banner of the WIN America Campaign, as reported a few days ago by Jesse Drucker in Bloomberg.

Biggest Tax Avoiders Win Most Gaming $1 Trillion U.S. Tax Break
Cisco, Oracle Corp. (ORCL), Microsoft Corp. (MSFT) and others formed a coalition called WIN America Campaign that plans to spend several million dollars pushing the issue.

“We simply don’t think it’s a good idea to do nothing while a trillion dollars sits overseas,” said Doug Thornell, a vice president for the firm who is advising the campaign.

Companies including Google Inc. (GOOG), Apple Inc. (AAPL) and Pfizer Inc. (PFE) are also pushing the proposed tax holiday, which would allow profits to return to the U.S. at a discounted 5.25 percent rate. Under current law, American companies can defer federal income taxes on most overseas earnings indefinitely. When they do return to the U.S., they’re taxed at the corporate rate of 35 percent -- with credits for foreign income taxes paid. Thus, companies paying little overseas face higher U.S. tax bills upon repatriation, and would get more benefit from the discount.

One way multinationals avoid taxes is through “transfer pricing,” transactions among subsidiaries that allow for allocating expenses to high-tax countries and profits to tax havens.

Cisco Systems Inc. (CSCO) has cut its income taxes by $7 billion since 2005 by booking roughly half its worldwide profits at a subsidiary at the foot of the Swiss Alps that employs about 100 people.

Cisco transfers a portion of the patent rights to technology developed in the U.S. to a Dutch unit, which sells some of the resulting products back to its parent for eventual distribution in the U.S., according to annual reports filed by the Amsterdam subsidiary. That means Cisco credits about $5 billion in U.S. sales annually to the Netherlands.

At the same time, most of the income from sales in countries like Germany, France and Japan [and the US], where statutory income tax rates average more than 30 percent, is ultimately transferred to Switzerland, meaning the other nations lose potential tax revenue. The result: Cisco’s international earnings have been taxed at about 5 percent since 2008, records show.

All told, Cisco has accumulated $31.6 billion in overseas earnings on which it has paid no U.S. income taxes yet, records show -- part of more than $1 trillion in U.S. companies’ offshore profits, according to data compiled by Bloomberg. In total, almost 90 percent of Cisco’s cash sits overseas.

Cisco, the largest maker of networking equipment, wants to save even more -- by asking Congress to waive most federal taxes due when multinationals bring such offshore earnings home. Chief Executive Officer John T. Chambers has led the charge for the tax holiday, which would be the second since 2004. He says it would encourage companies to “repatriate” as much as $1 trillion held abroad, spur domestic investment and create jobs.
[In the Homeland Investment scheme, they used these "talking points":

* Increasing domestic investment in plant, equipment, R&D and job creation;
* Increasing investments in business ventures in emerging technologies,
* Increasing funding for pension plans depleted by declines in the stock market;
* Improving the long term financial strength of U.S.-based companies by reducing domestic debt loads, strengthening corporate balance sheets, and lowering corporate bond rates; increasing dividends to shareholders (which can be productively redeployed); and raising equity market valuations by increasing funds available for share repurchases.

Actually, that last point was rather right on the main purpose of the supporters, and perhaps too blatant.]

“I create jobs overseas,” Chambers told interviewer Lesley Stahl on the CBS News program “60 Minutes” in March. “I build plants overseas and I badly want to bring that money back.”

The company needs that cash to prop up its share price.

U.S. companies used $312 billion they repatriated under a 2004 tax holiday largely for stock repurchases, while doing little direct hiring or domestic investment, according to a paper in the current issue of the Journal of Finance by professors at the University of Illinois, Harvard University, and the Massachusetts Institute of Technology. It was the latest in a series of studies that reached similar conclusions.

“Cisco complies with all global tax laws,” said John Earnhardt, a spokesman for the San Jose, California-based company, which makes switches, routers and other products, in an e-mailed statement. “In the past three years alone, Cisco (which has over 35,000 U.S. employees) has paid approximately $4.4 billion in U.S. federal corporate income taxes.” The company reported an effective tax rate last year of 17.5 percent, half the U.S. statutory rate.

While Treasury Secretary Timothy F. Geithner has expressed skepticism about a new repatriation break, Representative Kevin Brady, a Texas Republican, introduced a bill on May 11 that, like the 2004 measure, would not require companies to use their cash for hiring.

Brady declined to address why his measure does not include a hiring requirement. “With millions of Americans seeking work it makes good economic sense to temporarily lower the tax gate and allow up to a trillion dollars of stranded American profits to flow back into our economy,” he said in a statement.

The idea gained momentum last week after Senator Charles Schumer, a New York Democrat, said his party’s caucus was discussing whether short-term revenue from the holiday could fund an “infrastructure bank” to create jobs. Senator John Kerry, a Massachusetts Democrat, has also signaled that he may reconsider his previous opposition.

“Why should we reward firms for successfully gaming the tax system when we in turn are called on to make up the missing tax revenues?” said Kleinbard, a former corporate tax attorney at Cleary Gottlieb Steen & Hamilton LLP. “Much of these earnings overseas are reaped from an enormous shell game: Firms move their taxable income from the U.S. and other major economies -- where their customers and key employees are in reality located -- to tax havens.”

Labels: , ,

Friday, April 15, 2011

Check the ABS on those Wall Street Wives

Tracy Alloway posting on FT Alphaville is checking out the Wall Street Wives and their sexy ABS.

Taibbi takes aim at the Talf
here’s what we know: The company was founded in June 2009 with $14.87 million of investment capital, money that likely came from Christy Mack and Susan Karches. The two Wall Street wives then used the $220 million they got from the Fed to buy up a bunch of securities, including a large pool of commercial mortgages managed by Credit Suisse, a company [Christy's husband, former Morgan Stanley CEO] John Mack once headed.


With $220m in-hand the wives were free to do their part in kickstarting the Asset-Backed Securities (ABS). To paraphrase Tim Duy, back in 2008 and 2009 there were no bad assets, just misunderstood ones. The idea of the Talf was to revive demand for, and issuance of, ABS courtesy of Fed-provided funds.

However, as Taibbi notes, a key aspect of Talf is that the Fed doles out the money through what are known as non-recourse loans. So if the ABS bought by Christy and Susan bought turned sour, in theory they could just walk away.

The wives get most of the upside — the taxpayers get most of the downside.

Labels: ,

Sunday, November 21, 2010

It's all the same to me

Once upon a time, investing in the stock market involved choices, selections, discrimination. Buying a stock was like planning a vacation.

That was then. Now, it's all the same to me.

Now stock selection is Fast Money. And Lightening Rounds of Mad Money.

Now all markets are linked tighter than the threads in fine hotel-count sheets. Liquidity, and liquidity alone matters. The rising tide of liquidity has unloosed tsunami-defined market movements. Tsunamis are, after all, just liquidity events.

Now, it is a rather quaint idea to buy "a" stock. The stock pickers gave way to mutual funds, which gave way to WTF ETFs, and all of them are bound up in aggravating algorithms, whose main purpose is to make sure money runs with the pack.

Jason Zweig writes The Intelligent Investor every Saturday for The Wall Street Journal. A couple of his recent columns touch on this development.

Are ETFs a Menace—or Just Misunderstood?
A report released this week produced by researchers at the Kauffman Foundation, the Kansas City, Mo.-based institute that supports research on entrepreneurship, argues that ETFs are "radically changing the markets," raising the prospect of a "panic-driven market meltdown." ETFs are funds that hold all the securities in an index and themselves trade like a stock.

The proliferation of ETFs, the report contends, raises at least three worries. First, these funds have overconcentrated the ownership of thinly traded stocks. Second, they have led to an escalating number of trading failures. Third, ETFs could trigger another massive market swing like the May 6 "flash crash."

Let's start with concentration. According to the report, a single ETF, the iShares Russell 2000 Index Fund, is among the 10 largest holders of 1,737 stocks—many of which also are held by other iShares ETFs.

Yet ETFs aren't traditional mutual funds. At an ETF, the manager's job isn't to make judgments on single stocks, but merely to keep the portfolio as close to its index as possible. And, in contrast to a mutual fund, "no one stock represents a large portion of the typical ETF," says Gus Sauter, chief investment officer at Vanguard Group.

Since ETFs must buy the stocks in the index they track, regardless of price, it is legitimate to wonder whether values aren't getting out of whack as ETFs come to dominate the market.

Why Your Stock Portfolio Is Acting Like a Commodity Basket
In the past few years, many investors have concluded that commodities like oil, corn and gold offer independent returns that can diversify away the risks of stocks. But the correlations between stocks and commodities—the extent to which their prices move together—are in many cases the highest they have been in nearly 30 years.

This year, about 40% of the weekly movements in the S&P 500 index can be explained by weekly fluctuations in energy prices, says Michele Gambera, head of quantitative analysis at UBS Global Asset Management. That is twice the level of similarity over the past five years and roughly 20 times the level of the past two decades.

Some of the linkages between stocks and commodities are looking bizarre. This Thursday, the monthly correlation between sugar futures and the S&P 500 hit 67%, more than 10 times its level just six days earlier, says Howard Simons, strategist at Bianco Research. That is the third time this year that the linkage between sugar and stock prices surged above 60%—much higher than their long-term average of under 20%.

How on earth did sugar and stock prices get stuck together? Sugar, says Mr. Simons, is now both an "energy commodity" and a "growth story," since much of the Brazilian crop is used to produce ethanol. That gasoline additive is linked to crude-oil prices, which in turn are sensitive to monetary policy and global economic growth—the same factors driving stock prices.

Of course, correlation isn't causation; this could be a coincidence.

But there is another, less visible force at work, Mr. Simons says. Algorithmic trading programs, or "algos," automatically buy and sell a wide variety of assets based on mathematical models.

An algo doesn't know or care why two assets are moving together; it merely is programmed to recognize that they are doing so. As soon as a computer places bets that such a linkage in prices will persist, other traders—computers and humans alike—tend to take note and follow suit. That can be true, Mr. Simons says, whether or not a correlation is driven by fundamental economic factors.

"We've gotten to the Frankenstein point where algos are self-programming, and they evolve to chase these relationships," Mr. Simons says. "That's created a sheer wall of money that is forcing other people's behavior into the same pattern."

What's more, quantitative easing—the massive purchase of bonds by the Federal Reserve—and the global recovery have been bullish for just about every asset. But at past economic turning points, the correlation between stocks and commodities were lower than they are today.

For the foreseeable future, there will be plenty of periods in which diversification will seem to fail as tidal waves of money crash in and out of all assets at once.

As Guambat wrote back in 2006, just as stock markets began to go parabolic and then alcoholic,
A black box is not some fatcat in a pin-striped suit and a big cigar. It is a streak of cyberdata, a stateless, motherless virus hellbent to ambush, arbitrage and retreat faster than a ninja.

And they are everywhere, in to everything. Their bytes permeate every conceivable market, like a monstrous whale seiving the nutirients and little, bottom-of-the-food-chain investors and small players from the oceans of cash that trade the world's goods.

They derive their gains from diverse derivatives of incalculable numbers and varieties, trading the shadows of what used to be a currency or a commodity or a stock or a bond, but now come under the most obtuse and arcane of names that only financial rocket scientists can understand. Their trade is in ideas and concepts and notions and algorithms, not things and companies.

Back when stock picking became more treacherous, due in no small part to the huge and creative gaps in GAAP reporting, Enron accounting and Swiss bank/tax haven black holes, Guambat gave up stock picking and took up nose picking. Didn't make any more money, but didn't lose any, either.

Then, for reasons not really very well rationalized, Guambat got into trading the Australian stock market futures contract. It went well for a short while, but around about the time he wrote the words quoted above, he began to be overwhelmed with market moves that utterly made no sense to him, as tsunamis often take us by surprise.

So he's been beached for a while now, and with the regular tides now turning into a series of tsunamis, with tsunami sized ebbs and flows, he has no desire to go back in the water. It's just too treacherous, too rigged, and plays by games too fantastically contrived to offer the likes of Guambat any latitude for entertainment, let alone success.

If Las Vegas treated its gamblers the same way the stock markets now treat the casual punter, it would be in worse shape than it already is. Markets are simply a no-go zone for hobby traders any more.

If Wall Street wants to entice the likes of Guambat back to its markets, its going to have to build a better sandbox, and leave the concrete mixers to the big guys.

Labels: ,

Saturday, November 06, 2010

Simply put

The "price" of oil rises, the dollar falls. Any net difference for a dollar-based investor? Obviously, not much if any. But does the illusion distort other behaviour?

Apply that basic rule of thumb, now, to stock prices, and to an extent US Treasury bond prices, which is what these posts from the excellent FT Alphaville explains.

Bernanke’s genie released
The Bernanke put — aka that almost magical and metaphysical QE2 effect — appears to be having an impact on equity options skew already.

Simply explained: skew is what happens when the price of calls does not equal the price of puts exactly. That is to say when out out-of-the-money calls cost more or less than the equivalent puts.

So essentially, skew happens when the market is willing to pay more for protection on one particular direction in the underlying than the other.

Now here’s the interesting thing. Before Ben Bernanke’s Jackson Hole speech the skew in the S&P 500 had reached very high levels, with downside protection trading very expensive.

But as a second round of quantitative easing became increasingly expected by the market, that skew began to ease significantly.

This dynamic can be observed most directly by looking at the option market’s implied volatility skew, which measures the difference between the cost of puts and calls. As illustrated below, this declined significantly following the Fed’s hint at additional QE on September 21. Why buy downside protection when the Fed has done it for you?

Which is all well and good.

But there is another point that Curnutt makes, which is that the Fed may be unwittingly displacing all that volatility elsewhere:

…it looks like there’s a divergence between currency and equity volatility. The Fed may be compressing equity volatility but it’s incentivising currency volatility in its place.

He measures this divergence by looking at the correlation between the Vix index — which is derived from the implied volatility of the S&P 500 index — and the implied volatility of the UUP dollar index ETF [see the chart in the post].

All of which makes Curnutt conclude (our emphasis):

All in all, we are left thinking that there may be a derivatives market analogue to the “law of conservation of energy”. Perhaps it reads: “volatility cannot be created or destroyed, it can only change form”.

Which has to make you ask: will the granting of the market’s wish for liquidity actually lead to a much more sinister implication elsewhere?

Unwinding the US Treasury trade
there really is something perverse about the country undertaking the biggest bout of unconventional monetary policy ending up with the steepest curve.

Flattening yield curves are theoretically meant to stimulate the economy by lowering borrowing costs. (For those wondering, steep yield curves also have some benefits — like building banks’ balance sheets back up — more on which later).

this is from Bank of America Merrill Lynch:
The highlight of the Fed’s Treasury purchase program announced yesterday is the concentration of Treasury purchases in the 5y to 10y sector. This purchase program creates a negative supply of Treasuries to the private sector in 2011.

This will be most acutely felt in the belly of the curve, which is the preferred habitat of foreign institutions. The belly of the curve is also attractive because of favourable carry and roll down due to Fed hikes that are priced into the curve from 2013 onwards.

On the other hand, demand for the long end of the curve comes mostly from pension fund flows, which tends to be sporadic. This argues for a steep 5s-30s curve in the US.

In addition, the Fed is engaged in fighting disinflation and some pickup in inflation can be welcomed by the Fed … In this scenario, the long end will reflect an addition inflation risk premium, further steepening the US curve.
So $2,500bn worth of QEasing in the States has bought the Fed a steepening yield curve. Meanwhile, such a steep yield curve works to boost bank profits by upping the amount of money they can make borrowing short and lending long.

This was also one of the reasons why some commentators believed the Fed should actually be moving to flatten the curve. Suppressing the curve, it was thought, could decrease the attractiveness of the so-called US Treasury ‘curve trade’ and force banks to actually lend to the economy.

Flattening the yield curve to make banks lend to something other than the US Treasury is predicated on there actually being some private sector demand for loans (something which is still totally unclear), of course. But it might put a stop to some of the criticism currently being lobbed at the US central bank for its QE2 policy.

The below for example, is Reuters columnist Felix Salmon’s take on a 4,000-word piece by Shahien Nasiripour about winners and losers in the Fed’s monetary policy:

It’s truly outrageous that banks are lending more money to the U.S. government than they are to all commercial and industrial borrowers combined; well done to Nasiripour for connecting these dots and for providing a much-needed dose of outrage at the way in which
Bernanke’s monetary policy simply isn’t helping the broad mass of the U.S. population
.

Labels: , ,

Friday, October 08, 2010

The Ball and Chain of Title

It has been talked about round the blogosphere for yonks now that the financial gamesmanship of mortgage securitization, almost from the beginning, was running well in advance of the legal niceties.

In the olden days when Guambat was a young lawyer, a loan was made, attached to a promissory note and secured by a piece of property in a solemn, monogamist and ever-lasting marriage. Hardly any action involving title could be finalized without producing every piece of paper signed off by every interested party, notarized and certified under penalty of perjury.

But securitization tore apart that happy home, slicing, dicing, and re-splicing all the rights, powers and interests in ways previously seen as impractical legally, if not a bit over the top in a sluttish sense.

Whereas the one heretofore monogamist mortgage once knew its related parts, now who knew who owned, controlled or beneficially or otherwise benefited from capital, income or pee stream?

And if the marriage broke up for whatever reason, what King could possibly put the Humpty Dumpty melange of interests together again?

Well, it's beginning to look like a King-hit on the entire mortgage industry. The second fallout from the screaming securitization of the financial wizards.

Will this one be as bail-outable as the first? Shall Guambat begin passing the plate?

The Foreclosure Scandal Begins to Hit Home

In foreclosure controversy, problems run deeper than flawed paperwork

Millions of U.S. mortgages have been shuttled around the global financial system - sold and resold by firms - without the documents that traditionally prove who legally owns the loans.

Now, as many of these loans have fallen into default and banks have sought to seize homes, judges around the country have increasingly ruled that lenders had no right to foreclose, because they lacked clear title.

These fundamental concerns over ownership extend beyond those that surfaced over the past two weeks amid reports of fraudulent loan documents and corporate "robo-signers."

The court decisions, should they continue to spread, could call into doubt the ownership of mortgages throughout the country, raising urgent challenges for both the real estate market and the wider financial system.

For struggling homeowners trying to avoid foreclosure, it could mean an opportunity to challenge the banks they argue have been unhelpful at best and deceptive at worst. But it also threatens to leave them in prolonged limbo, stuck in homes they still can't afford and waiting for the foreclosure process to begin anew.

For big banks, "there's a possible nightmare scenario here that no foreclosure is valid," said Nancy Bush, a banking analyst from NAB Research. If millions of foreclosures past and present were invalidated because of the way the hurried securitization process muddied the chain of ownership, banks could face lawsuits from homeowners and from investors who bought stakes in the mortgage securities - an expensive and potentially crippling proposition.

The company, known as MERS, was created more than a decade ago by the mortgage industry, including mortgage giants Fannie Mae and Freddie Mac, GMAC, and the Mortgage Bankers Association.

MERS allowed big financial firms to trade mortgages at lightning speed while largely bypassing local property laws throughout the country that required new forms and filing fees each time a loan changed hands, lawyers say.

The idea behind it was to build a centralized registry to track loans electronically as they were traded by big financial firms. Without this system, the business of creating massive securities made of thousands of mortgages would likely have never taken off. The company's role caused few objections until millions of homes began to fall into foreclosure. In August, the Maine Supreme Court threw out a foreclosure case because "MERS did not have a stake in the proceedings and therefore had no standing to initiate the foreclosure action."

In May, a New York judge dismissed another case because the assignment of the loan by MERS to the bank HSBC was "defective," he said. The plaintiff's counsel seemed to be "operating in a parallel mortgage universe," the judge wrote.

Also in May, a California judge said MERS could not foreclose on a home, because it was merely a representative for Citibank and did not own the loan.

On the other hand, Minnesota legislators passed a law stating that MERS explicitly has the right to bring foreclosure cases. And on its Web site and in e-mails, MERS cites numerous court decisions around the country that it says demonstrate the company's right to act on behalf of lenders and to undertake foreclosures.

Kentucky lawyer Heather Boone McKeever has filed a state class-action suit and a federal civil racketeering class-action suit on behalf of homeowners facing foreclosure, alleging that MERS and financial firms that did business with it have tried to foreclose on homes without holding proper titles.

"They have no legal standing and no right to foreclose," McKeever said. "If you or I did this one time, we'd be in jail."

Flawed Foreclosure Documents Thwart Home Sales
With home sales this past summer at the lowest level in more than a decade, real estate is ill-prepared to suffer another blow. But as a scandal unfolds over mortgage lenders’ shoddy preparation of foreclosure documents, the fallout is beginning to hammer the housing market, especially in states like Florida where distressed properties are abundant.

Three major mortgage lenders — Bank of America, GMAC Mortgage and JPMorgan Chase — have said they are suspending foreclosures in the 23 states where they first need a judge’s approval. They are also waving off Fannie Mae from selling any of the foreclosed homes whose loans they sold to Fannie.

The companies say they are reviewing their operations after disclosures that employees signed documents without determining the accuracy of the material, as is required by law.

Those reviews are throwing into limbo hundreds of thousands of foreclosures and pending home sales, analysts estimate, though the lenders and Fannie Mae have been mostly silent about precise numbers and other specifics.

More broadly, the revelations about the sloppy paperwork are emboldening homeowners and law enforcement officials in many states to question whether lenders rightfully hold the notes underlying foreclosed properties — further chilling the housing market.

Ohio Attorney General Sues GMAC Over Improper Affidavits; Maximum Damages Exceed $10 Billion
So much for the idea that the affidavit problem is a mere technicality and a mere operational hassle for the banks. They had clearly viewed complying with their own agreements as an option, not a requirement, with the savings for cutting corners only somewhat offset by the costs of getting caught from time to time.

Some jurisdictions aren’t buying the banks’ “crime pays” logic. These abuses challenge the basic principles of the rule of law.

Admittedly, the affidavit problem is a secondary front in the overall bank “my dog ate your mortgage” mess. But the fact that a supposedly minor problem may not prove to be so minor illustrates that all these battles will be hard fought and thus more costly than the banks’ breezy assurances would lead one to believe.

The ultimate objective is to break the excuses that the banks have been using to avoid doing serious principal writedowns. If one state is able to get a mass settlement, whether in the course of private action or state attorney general suits and investigations, it will be a precedent that other banks will find difficult to ignore.

Ohio Attorney General Sues GMAC, Seeks $25,000 Per False Affidavit
Richard Cordray, the Attorney General for the state of Ohio has filed a lawsuit in Lucas County (Toledo) Common Pleas Court against GMAC Mortgage and their parent company Ally Financial, in a suit which names Jeffrey Stephan, the infamous “robo-signer” who signed off on up to 10,000 foreclosures a month across the country with affidavits, without verifying the information in the foreclosure documents. The lawsuit alleges fraud on the part of GMAC, along with violations of the Ohio Consumer Sales Practices Act, in filing false affidavits to mislead the courts in what they describe as “hundreds” of Ohio foreclosure cases. And, the Attorney General is treating every single false affidavit filed in an Ohio court as a separate violation, with a fine of up to $25,000, plus additional restitution for the homeowner of an unspecified amount.

“It is now becoming clear that fraud, deception, and an utter disregard for accuracy are in part to blame for our national foreclosure disaster,” Cordray said in prepared remarks. “What we are seeing and hearing strikes at the very foundation of the rule of law in our court system… Clearly any fraud or deception that has contributed to this state of affairs must be stopped, and those responsible must be held accountable.”

When challenged by one reporter about the fact that the borrowers were in fact delinquent and that merits some action on the part of the lender, Cordray struck back. “What each side merits is that proper legal processes be carefully followed… If we would file a case with an affidavit we know to be false, that is seen as a very serious matter by the court. I don’t see why this should be taken any more lightly.”

Is HR3808 The Equivalent Of TARP 2 And Obama's "Get Out Of Bail" Gift Card For The High Frequency Signing Scandal?
Now that the High Frequency Signing (HFS, not to be confused with HFT) scandal is mainstream, and virtually every single foreclosure in the US in the past several years is under question, with the impact on mortgage servicers (who just happen to be the TBTF banks) could be just as dire as the fallout from the credit crunch, it appears that the get out of jail card for the banking syndicate has once again materialized, this time in the form of bill HR3808: Interstate Recognition of Notarizations Act of 2009, sponsored by Republican representative Robert Aderholt.

In summary, the bill requires all federal and state courts to recognize notarizations made in other states. That's the theoretical definition: the practical one - the legislation, if enacted, could protect bank and mortgage processors from liability for false or improperly prepared documents.

Bank foreclosure cover seen in bill at Obama's desk
The timing raised eyebrows, coming during a rising furor over improper affidavits and other filings in foreclosure actions by large mortgage processors such as GMAC, JPMorgan and Bank of America.

"It is troubling to me and curious that it passed so quietly," Thomas Cox, a Maine lawyer representing homeowners contesting foreclosures, told Reuters in an interview.

A deposition made public by Cox was what first called attention to improper affidavits by GMAC. Since then, GMAC, JPMorgan and others have halted foreclosure actions in many states after acknowledging that they had filed large numbers of affidavits in which their employees falsely attested that they had personally reviewed records cited to justify the foreclosures.

Cox said the new obligation for courts to recognize notarizations of documents filed by big, out-of-state companies, would make it more difficult and costly to challenge the validity of the documents.

The law, the "Interstate Recognition of Notarizations Act," requires all federal and state courts to recognize notarizations made in other states.

The law specifically includes "electronic" notarizations stamped en masse by computers. Currently, only about a dozen states allow electronic notarizations, according to the National Notary Association.

After languishing for months in the Senate Judiciary Committee, the bill passed the Senate with lightning speed and with hardly any public awareness of the bill's existence on September 27, the day before the Senate recessed for midterm election campaign.

The bill's approval involved invocation of a special procedure. Democratic Senator Robert Casey, shepherding last-minute legislation on behalf of the Senate leadership, had the bill taken away from the Senate Judiciary committee, which hadn't acted on it.

The full Senate then immediately passed the bill without debate, by unanimous consent.

Boiler Rooms and Foreclosure Mills: A Brief History of America's Mortgage Industry
Just about every corner of America's mortgage industry has been blemished by significant levels of fraud over the past decade.

On the front end of the process, for example, many mortgage pros used "boiler-room" salesmanship to peddle loans to borrowers who didn't understand what they were getting and couldn't afford their loans in the long run. To make these deals go through, some workers forged borrowers' signatures on key disclosure documents, pressured real estate appraisers to inflate home values, and created fake W-2 tax forms that exaggerated loan applicants' earnings.

At Ameriquest Mortgage, one of the companies I focus on in my new book about the subprime mortgage debacle, The Monster, this sort of cut-and-paste document production was so common employees joked that the work was being done in "The Lab" or the "Art Department."

Little was done to stop the bad practices when they were happening. Former Federal Reserve Chairman Alan Greenspan would later explain to CBS' 60 Minutes: "While I was aware a lot of these practices were going on, I had no notion of how significant they had become until very late. I didn't really get it until very late in 2005 and 2006." The Fed took no action even when it became aware of the problems, he said, because "it's very difficult for banking regulators to deal with that."

Congress and other powers in Washington failed to get the facts and act the first time around -- when lenders were engaged in a frenzy of predatory lending. The foreclosure scandal is a second chance for lawmakers and bureaucrats to prove that they can ferret out the truth and take action.

In the Last Four Months, Three Homeowners Have Sued Bank of America for Mistakenly Foreclosing on Their Homes
Some 2.8 million homeowners faced the threat of foreclosure last year, but it wasn't supposed to happen to Charlie and Maria Cordoso. In 2005, the New Bedford, Mass. couple paid in full -- in cash -- for a house in Springville, Fla., and rented it out with plans eventually to use the home as a retirement getaway.

They said they were shocked to learn earlier this month that Bank of America had locked them out and removed their clothing and furniture from the property.

"It's a national issue," said Joseph deMello, one of lawyers representing the Cordosos.

Bank of America actually had planned to foreclose on a property about 10 houses away but mistakenly went after the Cordosos' home instead, deMello said.

Foreclosure experts like Rick Sharga, of California-based foreclosure tracking firm RealtyTrac, say cases like these are symptomatic of a broken system strained by the housing boom and bust.

Banks have been "unable to efficiently handle the volume of distressed assets that are coming through," Sharga said. "We also are seeing the results of what had been less-than-rigorous paperwork and documentation management over the last decade or so as loans became commodities that were packaged, sold, repackaged and resold."

Sharga said that while human error contributed to errant foreclosures in the past, they're happening with greater frequency now as banks find themselves overwhelmed with delinquent mortgages.

Updating the US foreclosure scandal

Bombshell of Foreclosure Fraud – Full Deposition of TAMMIE LOU KAPUSTA Law Office of David J Stern

Labels: , , ,

Wednesday, September 01, 2010

No rendition for Moody's European unit up to its nexus in fraud-like behaviour

Moody's Investor Services (MIS) was born of an American, John Moody, around the turn of the Nineteenth into the Twentieth Century. And, my, how it has grown.

According to its resume, "Moody's is an essential component of the global capital markets, providing credit ratings, research, tools and analysis that contribute to transparent and integrated financial markets. Moody's Corporation (NYSE: MCO) is the parent company of Moody's Investors Service."

The Securities Exchange Commission regulates American companies, especially credit reporting agencies. Moody's became a nationally recognized statistical rating organization ("NRSRO"), registered with SEC, after the middle of 2007. But just prior to that time, Moody's European operations bad a boo-boo. A not insignificant one.

But one apparently safely separated from the SEC by the Atlantic Ocean. That is the story told by the SEC itself in its Report of Investigation Pursuant to Section 21(a) of the Securities Exchange Act of 1934: Moody's Investors Service, Inc. released August 31st:
In the summer of 2006, MIS began developing a methodology for rating notes issued by a newly created CPDO.

The rating committee responsible for the credit ratings of the CPDO notes met in France and the United Kingdom. The CPDO notes were arranged by European banks and marketed in Europe.

Because CPDO notes were new instruments, MIS had no existing model for use in rating them. MIS created a model and in September 2006 gave the notes issued by the newly created CPDO issuer an Aaa credit rating. By the end of 2006, MIS had issued credit ratings for notes issued by an additional eleven CPDO issuers. The notes of all twelve CPDO issuers were marketed in Europe.

In January 2007, an MIS analyst in New York, assisting on a CPDO deal with a United States investment bank, was asked to determine why the MIS CPDO model was not generating the same output as the investment bank's model.

Upon examination, the analyst discovered a coding error in the MIS model. The coding error upwardly impacted by 1.5 to 3.5 notches the model output used to determine MIS credit ratings for notes issued by eleven CPDO issuers.

The CPDO notes with affected credit ratings had a combined notional value of just under $1 billion.

MIS subsequently held several internal rating committee meetings in France and the United Kingdom to address the coding error.

MIS corrected the coding error on February 12, 2007, but made no changes to the outstanding credit ratings for CPDO notes at that time.

Internal e-mails show that committee members were concerned about the impact on MIS's reputation if it revealed an error in the rating model. The committee was comprised of senior level staff, including two Team Managing Directors, two Vice President-Senior Credit Officers, and a Vice President-Senior Analyst.

In declining to downgrade the credit ratings, the committee considered the following inappropriate non-credit related factors:
>(i) that downgrades could negatively affect Moody's reputation in light of ongoing negative media focus in Europe on Moody's Joint Default Analysis;
>(ii) that downgrades could impact investors who relied on the original ratings; and
>(iii) the desire not to validate the criticisms of Moody's ratings of CPDOs that had been made by a competitor and covered in the local media.
The actions of the rating committee that evaluated the affected credit ratings for the CPDO notes did not comply with MIS' own Core Principles.

Members of the rating committee involved in the monitoring of CPDO ratings allowed concerns regarding Moody's reputation and other non-credit related considerations to influence decisions not to downgrade the affected CPDOs.

Further, we conclude that, in early 2007, members of the European rating committee believed they could violate MIS's procedures without detection

[How-ever,] Because of uncertainty regarding a jurisdictional nexus to the United States in this matter, the Commission declined to pursue a fraud enforcement action.

Labels: , , ,

Thursday, June 24, 2010

Putting your money where their mouth is

Guambat is sure there must be some social value somewhere in the private equity concept, but he'd be hard pressed to put a finger, let alone a paw, on it. Maybe once, if ever, the government starts to tax their income as ordinary income as it would for the rest of us, it might be easier to spot.

It might also be interesting to see the result of the following "conundrum" and the fall out it generates before trying to make that decision.

Private Equity Firms Have Billions and Nowhere to Spend It
Corporate buyout specialists generally raise money from big investors and then buy undervalued or underappreciated companies. To maximize investment returns, they typically leverage their cash with loans from banks or bond investors.

Critics contend that leveraged buyouts can saddle takeover targets with dangerous levels of debt. But unlike indebted homeowners, highly leveraged companies under the care of private equity have so far dodged the big bust many have predicted.

After an unprecedented burst of buyouts during the boom leading up to 2008, a vast majority of these companies are hanging on. Whether they will avoid a reckoning is uncertain.

Private equity funds generally tie up investors’ money for 10 years. But they typically must invest all the money within the first three to five years of the funds’ life.

For giant buyout funds raised in 2006 and 2007, at the height of the bubble, time is short. They must invest their money soon or return it to clients — presumably along with some of the management fees the firms have already collected. Some of the industry’s biggest players, like David M. Rubenstein of the Carlyle Group, Henry Kravis of Kohlberg Kravis Roberts and David Bonderman of TPG, have more than $10 billion apiece in uncommitted capital — what is known as “dry powder” — according to Preqin, an industry research firm.

A big drop in returns would be particularly vexing for pension funds, which are counting on private equity, hedge funds and other so-called alternative investments to help them meet their mounting liabilities.

Some buyout firms are asking their clients for more time to search for companies to buy. Many more are rushing to invest their cash as quickly as possible, whatever the price.

Still, those with dry powder are bidding aggressively, in the United States, Europe and Asia.

Labels: ,

Thursday, June 10, 2010

A boatload of sugar helped the poison go down

AIG’s Government Rescue Had ‘Poisonous’ Effect, U.S. Panel Says
“The government’s actions in rescuing AIG continue to have a poisonous effect on the marketplace,” said the Congressional Oversight Panel panel, led by Harvard University law professor Elizabeth Warren.

“The AIG rescue demonstrated that Treasury and the Federal Reserve would commit taxpayers to pay any price and bear any burden to prevent the collapse of America‘s largest financial institutions and to assure repayment to the creditors doing business with them.”

American International Group Inc.’s bailout had a “poisonous” effect on the U.S. financial system because it demonstrated the government would protect firms from their own risk-taking.

Treasury Secretary Timothy F. Geithner said in January. Geithner, 48, executed the bailout while he led the Federal Reserve Bank of New York in 2008.

AIG leaders allowed the firm to accumulate “staggering amounts of risk” in derivatives and other areas, the panel said.

The breadth of operations weren’t “matched by a coherent regulatory structure to oversee its business.” The Office of Thrift Supervision had oversight of the parent company and failed to limit risks from swaps, the panel said.

Regulators have said that they were forced to save AIG to prevent a wave of failures that a collapse would have sparked.

The report “overlooks the basic fact that the global economy was on the brink of collapse and there were only hours in which to make critical decisions,” Andrew Williams, a Treasury spokesman, said in an e-mailed statement.

“We have learned from that experience and have been fighting for more than a year to give the government authority to put firms, like AIG, out of existence when their failure poses a danger to our economic system.”

If Congress truly has learned anything from the experience, they should be passing rock solid and loop-hole free financial reforms, including the Volker Rule, rather than continue to pander to the banking lobbyists as has been their habit.

Write your Senator, write your Congresswoman, and insist on the Volker Rule. Guambat would, but being a dual Guamanian/Australian doesn't give him any such representation.


Congressional watchdog criticizes rescue of AIG
The firm was nearly wiped out by credit default swaps, which amount to insurance [sic: in reality, bets] against the risk that mortgages and other debts will go bad. Treasury and the Fed pulled AIG back from the brink in September 2008.

When the housing market collapsed, AIG couldn't meet its obligations to its counterparties, including Goldman Sachs and JPMorgan Chase. In the bailout, the Fed paid the counterparties 100 cents on the dollar.

The government relied only on Goldman Sachs and JPMorgan to arrange a private rescue of AIG, a conflict of interest because, as AIG counterparties, "They would have been among the largest beneficiaries of a taxpayer rescue."

Labels: , , ,

Saturday, April 24, 2010

Rating credit agencies rate right up there

Wall Street got away with the bonus bucks and bail out because of its influence in Washington and on credit ratings agencies. Had either of those two other institutions failed to play ball, Wall Street would never have got to first base with its credit shenanigans.

This post is (again) about the agencies.

How credit watchdogs fueled the financial crisis
Lawmakers are now asserting that credit rating agencies (CRAs) like Moody's Investors Service and Standard and Poor's Ratings Services failed to expose the lurking dangers.

"Rating agencies continue to create an even bigger monster - the CDO Market," wrote one S&P employee in an internal e-mail in December of 2006. "Let's hope we are all wealthy and retired by the time this house of cards falters. :o)."

The Subcommittee is accusing the credit agencies of contributing to the crisis in several major ways: By using ineffective models to measure risk, by inflating ratings because of pressure from banks, by ignoring early warning signs and by failing to quickly disclose the risk on existing products once it was discovered.

In his testimony, Richard Michalek, former vice president of the Structured Derivative Products Group at Moody's admitted that he felt constant pressure to accept deals, even if they looked risky.
The Congressional watchdogs, of course, bear as much blame, what with their setting the so-called "investment" bank dogs off the regulatory leash and allowing "mark-to-bark" accounting gimmicks. But Guambat digresses.

Another ratings agency failure is suggested in the following article: the failure to have enough knowledge of what they were dealing with to properly to dig deep enough to even ask the right questions.

UPDATE 1-Ex-Moody's exec didn't know Paulson shorted Abacus
A former senior official at Moody's Corp said he would have liked to have known that hedge fund manager John Paulson was shorting a Goldman Sachs Group Inc derivatives product when Moody's was rating it.

"I did not know that. I'm fairly sure that my staff did not know either" about Paulson's involvement, said Eric Kolchinsky

Labels: ,

Wednesday, April 21, 2010

The short heard - but not seen - around the world

Questions for Banks That Put Together Deals
C.D.O. transactions are not publicly traded, so it is difficult to get a full picture of the market’s size. But research suggests it is huge. Thomson Reuters estimates that sales of C.D.O.’s peaked at $534.2 billion in 2006, from $68.6 billion in 2000. Even in 2007, when the housing market was starting to crumble, Wall Street created an estimated $486.8 billion in new C.D.O.’s.

Many banks on Wall Street and in Europe were even bigger players in the types of complex investment deals that Goldman is now defending. Merrill Lynch was at the top of the heap, assembling $16.8 billion worth between 2005 and 2008, according to a new report by Credit Suisse.

Once the air started coming out of the housing market and there were no more mortgage bonds to sell, they created synthetic C.D.O.’s, whose supply was unlimited because they did not rely on hard assets.

UBS put together $15.8 billion worth of similar products, according to the Credit Suisse estimates, while JPMorgan Chase and Citigroup each created more than $9 billion worth. Goldman Sachs was a comparatively small issuer, at $2.2 billion.

C.D.O.’s, which produced much of the financing for the mortgage explosion, are at the heart of the Securities and Exchange Commission’s civil fraud case against Goldman Sachs — as well as a broader S.E.C. investigation of sales and disclosure practices at many Wall Street firms.

Until the bottom fell out, these instruments also powered an age of riches on Wall Street. Initially, bundling mortgage bonds into C.D.O.’s helped open the spigot of easy money that allowed Americans to buy more house than they could afford.

But Wall Street, as it is wont to do, took the concept to another level, creating securities that allowed investors to make side bets on the housing market. Known as synthetic C.D.O.’s, they did not raise money for home loans or serve any other broad economic purpose.

Instead, like a casino offering blackjack along with slot machines and Texas hold ’em, they were just one more way to bet against the housing market.

Crucial to the case against Goldman is the question of whether the firm should have disclosed that an investor who was betting against the securities in the portfolio also helped select them. In legal filings, Goldman argues that it was not standard industry practice to make such a disclosure.

Magnetar, a Chicago hedge fund, also invested in C.D.O.’s that it then bet against, without disclosing its role, according to an investigation by ProPublica, a nonprofit journalism organization. Magnetar has denied that it picked individual securities, however, adding that its investment strategy was market-neutral.

The threat of more litigation represents the abrupt end to what was a golden era on Wall Street.

Labels: ,

Sunday, April 18, 2010

Channeling Interfluidity

Over at the bottom of the links list on the right is the only finance/economics/market link Guambat provides. Steve Waldman writes that one. Guambat is so envious. After getting all the preceding posts off Guambat's puny chest, he wandered over to see what Steve had to say. Steve's take on this Goldman Sachs thing is thoughtful, personal, provocative, prosaically expressed. As you'd expect. Steve is even more wordy that Guambat, but it is worthy because of his prose. There are extracts following, but to get the full flavor, argument and understanding of his message, you should go read the whole piece. Take your time, it's worth it.
Goldman-plated excuses
My first reaction, upon reading about the SEC’s complaint against Goldman Sachs was to shrug. If that’s the worst the SEC could dig up, I thought, there’s way too much that’s legal.

Had you asked me, early Friday afternoon, what would happen, I would have pointed to the “global settlement” seven years ago. Then as now, investment banks were caught fibbing to keep the deal flow going (then via equity analysts who hyped stocks they privately did not admire). The settlement got a lot of press, the banks were slapped with fines that sounded big but didn’t matter, promises were made about “chinese walls” and stuff, nothing much changed.

The SEC threw Goldman a huge softball by focusing almost entirely on the fibs of a guy who calls himself “the fabulous Fab” and makes bizarre apocalyptic boasts. Given the apparent facts of this case, phrases like “bad apple” and “regret” and “large organization” and “improved controls” would have been apropos. It’s almost poignant: The smart thing for Goldman would be to hang this fab Fab out to dry, but whether out of loyalty or arrogance the firm is standing by its man.

But Goldman’s attempts to justify what occurred, rather than dispute the facts or apologize, could be the firm’s death warrant. The brilliant can be so blind.

The core issues are simple. Goldman arranged the construction of a security, a “synthetic CDO”, which it then marketed to investors. No problem there, that’s part of what Goldman does. Further, the deal wasn’t Goldman’s idea. The firm was working to serve a client, John Paulson, who had a bearish view of the housing market and was looking for a vehicle by which he could invest in that view. Again, no problem.

I’d argue even argue that, had Goldman done its job well, it would have done a public service by finding ways to get bearish views into a market that was structurally difficult to short and prone to overpricing.

Goldman could, quite ethically, have acted as a broker. Goldman could have tailored a security or derivative contract to Paulson’s specifications and found a counterparty willing to take the other side of the bet in full knowledge of the disagreement.

Investors get to disagree. But it did need to ensure that all parties to an arrangement that it midwifed understood the nature of the disagreement, the substance of the bet each side was taking. And it did need to ensure that the parties knew there was a disagreement.

Goldman argues that the nature of the security was such that “sophisticated investors” would know that they were taking one of two opposing positions in a disagreement:
"These investors also understood that a synthetic CDO transaction necessarily included both a long and short side."
That line is so absurd, brazen, and misleading that I snorted when I encountered it.

Of course it is true, in a formal sense. Every financial contract — every security or derivative or insurance policy — includes both long and short positions.

So why did Goldman put that line in their deeply misguided press release? One word: derivatives. The financially interested community, like any other group of humans, has its unexamined clichés.

One of those is that derivatives are zero sum contests between ‘long’ investors and ’short’ investors whose interests are diametrically opposed and who transact only because they disagree. By making CDOs, synthetic CDOs sound like derivatives, Goldman is trying to imply that investors must have known they were playing against an opponent, taking one side of a zero-sum gamble that they happened to lose.

Of course that’s bullshit. Synthetic CDOs are constructed, in part, from derivatives. (They are built by mixing ultrasafe “collateral securities” like Treasury bonds with credit default swap positions, and credit default swaps are derivatives.) But investments in synthetic CDOs are not derivatives, they are securities.

While the constituent credit default swaps “necessarily” include both a long and a short position, the synthetic CDOs include both a long and a short position only in the same way that IBM shares include both a long and a short position.

Synthetic CDOs were composed of CDS positions backed by many unrelated counterparties, not one speculative seller. Goldman’s claim that “market makers do not disclose the identities of a buyer to a seller” is laughable and disingenuous.

A CDO, synthetic or otherwise, is a newly formed investment company. Typically there is no identifiable “seller”. The investment company takes positions with an intermediary, which then hedges its exposure in transactions with a variety of counterparties.

The fact that there was a “seller” in this case, and his role in “sponsoring” the deal, are precisely what ought to have been disclosed. Investors would have been surprised by the information, and shocked to learn that this speculative short had helped determine the composition of the structure’s assets. That information would not only have been material, it would have been fatal to the deal, because the CDO’s investors did not view themselves as speculators.

I have little sympathy for CDO investors.

Wait, scratch that. I have a great deal of sympathy for the beneficial investors in CDOs, for the workers whose pensions won’t be there or the students at colleges strapped for resources after their endowments were hit.

But I have no sympathy for their agents and delegates, the well-paid “professionals” who placed funds entrusted them in a foolish, overhyped fad. But what investment managers believed about their hula-hoop is not what Goldman now hints that they believed.

Investors in synthetic CDOs did not view themselves as taking one side of a speculative gamble against a “short” holding opposite views. They had a theory about their investments that involved no disagreement whatsoever, no conflict between longs and shorts. It went like this:
There is a great deal of demand for safe assets in the world right now, and insufficient supply at reasonable yields. So, investors are synthesizing safe assets by purchasing riskier debt (like residential mortgage-backed securities) and buying credit default swaps to protect themselves. All that hedging is driving up the price of CDS protection to attractive levels, given the relative safety of the bonds.

We might be interested in capturing those cash flows, but we also want safe debt. So, we propose to diversify across a large portfolio of overpriced CDS and divide the cash flows from the diversified portfolio into tranches. If we do this, those with “first claims” on the money should be able to earn decent yields with very little risk.
I don’t want to say anything nice about that story. The idea that an investor should earn perfectly safe, above-risk-free yields via blind diversification, with little analysis of the real economic basis for their investment, is offensive to me and, events have shown, was false.

But this was the story that justified the entire synthetic CDO business, and it involved no disagreement among investors. According to the story, the people buying the overpriced CDS protection, the “shorts” were not hoping or expressing a view that their bonds would fail. They were hedging, protecting themselves against the possibility of failure.

The RMBS investors may have believed that they were overpaying for protection, just as CDO buyers did, just as we all knowingly and happily overpay for insurance on our homes. Shedding great risk is worth accepting a small negative expected return.

That derivatives are a zero-sum game may be a cliché, but it is false. Derivatives are zero-sum games in a financial sense, but they can be positive sum games in an economic sense, because hedgers are made better off when they shed risk, even when they overpay speculators in expected value terms to do so. (If there are “natural” hedgers on both sides of the market, no one need overpay and the potential economic benefits of derivatives are even stronger. But there are few natural protection sellers in the CDS market.)

Perhaps the bankers thought Paulson was a patsy, that his bearish bets were idiotic and they were doing investors no harm by hiding his futile meddling. Perhaps, as Felix Salmon suggests, the employees doing the deal had little reason to care about whether the part of the structure Goldman retained performed, as long as they could book a fee. But all of that is irrelevant, assuming the SEC has the facts right.

Investors in Goldman’s deal reasonably thought that they were buying a portfolio that had been carefully selected by a reputable manager whose sole interest lay in optimizing the performance of the CDO.

They no more thought they were trading “against” short investors than investors in IBM or Treasury bonds do. In violation of these reasonable expectations, Goldman arranged that a party whose interests were diametrically opposed to those of investors would have significant influence over the selection of the portfolio.

Goldman misrepresented that party’s role to the manager and failed to disclose the conflict of interest to investors. That’s inexcusable.

Was it illegal? I don’t know, and I don’t care. Given the amount of CYA boilerplate in Goldman’s presentation of the deal, maybe they immunized themselves.

But the firm’s behavior was certainly unethical. If Goldman cannot acknowledge that, I can’t see how investors going forward could place any sort of trust in the firm.

As mentioned, Interfluidity can be provocative, and this post certain generated a lot of 2-way dialogue. If you want to try to think your way through the GS imbroglio, you could start with his post and the comments. He's also continuing to publicly think his way through the issues, so keep up with his posts. If you want to soundbite your way through the GS "story", you can read most of the press. In either case, Guambat highly recommends his own take, suggested in the various posts on this subject over the least coupla days.

Labels: , ,

Saturday, April 17, 2010

This is now, that was then: a moral in 4 parts


I. THIS IS NOW ...


Paulson, Looking to Go Short on Mortgages, Found a Willing Partner
Paulson & Co. asked banks including Goldman Sachs Group Inc. to structure mortgage deals that would include some of the poorest quality mortgages. The hedge fund's plan: bet against the deals and then hope for a bursting of the housing bubble

One senior banker at Bear Stearns Cos. turned down the business. He questioned the propriety of selling deals to investors that a bearish client was involved in putting together, according to people familiar with the matter.

Goldman Sachs and Deutsche Bank AG were among those that played ball.
Merrill Lynch Used Same Alleged Fraud as Goldman, Bank Claims
“This is the tip of the iceberg in regard to Goldman Sachs and certain other banks who were stacking the deck against CDO investors,” said Jon Pickhardt, an attorney with Quinn Emanuel Urquhart Oliver & Hedges, who is representing Netherlands-based Rabobank.

II. THIS WAS THEN ...

How to gain from their pain October 24, 2006
About 18 percent of all mortgages issued in the first half of the year were to borrowers considered most likely to default, such as those with high credit-card balances, up from 2.4 percent in 1998, based on data from the Mortgage Bankers Association.

The ABX index, created by London-based Markit Group Ltd., measures prices of credit-default swaps based on the $565 billion of bonds secured by so-called subprime mortgages and home-equity loans.

Credit-default swaps are financial instruments based on bonds and loans that are used to speculate on the ability of borrowers to repay debt.

"The unequivocally bad housing data we've seen" is prompting investors to seek to profit from potential declines in mortgage-backed securities, said Greg Lippmann, the head of asset-backed trading at Deutsche Bank AG in New York who helped create the ABX indexes in January.

A Merrill Lynch & Co. index of debt securities derived from home-equity loans rated AA to BBB is having its worst month this year, falling 0.01 percent. They have returned 4.54 percent since the end of December. Banks and lenders such as Countrywide Financial Corp. in Calabasas, California, and Washington Mutual Inc. of Seattle typically take mortgages and package them into bonds for sale to investors.
A nice, big, juicy subprime stake October 30, 2006
Since the beginning of 2002, banks and specialized lenders such as ACC Capital Holdings Corp.'s Ameriquest Mortgage Co., New Century Financial Corp., and H&R Block Inc.'s Option One Mortgage Corp. have made some $2.2 trillion in loans. That is more than five times the amount in the preceding five-year period, and includes a growing share of "affordability" products such as "piggyback," "interest-only" and "no-doc" loans. These products, respectively, allow borrowers to avoid a down payment, make extra-low payments in a loan's early years, and state their income without supporting documentation. Subprime loans' actual interest rates are typically much higher than those on more traditional "prime" loans.

A recent study by two researchers at the Federal Reserve Bank of Chicago, Jonas Fisher and Saad Quayyum, suggests that subprime lending alone could account for close to half of the four-percentage-point rise in the ownership rate since 1995.

At about the same time, in early 2005, Wall Street bankers were developing a new kind of derivative contract that would allow investors such as Mr. Whalen to make bets based on their misgivings. Called a credit-default swap, it had previously been applied mainly to corporate and sovereign bonds. Like an insurance contract, it pays off if a subprime-backed bond suffers a certain amount of losses to defaults.

In January 2005, for example, Mr. Whalen bought an insurance contract on the Long Beach Mortgage Loan Trust 2004-2, the bond into which Mr. Spirou's loan had been packaged. He agreed to pay the counterparty, Citigroup Inc., $20,300 a year for a contract that would pay up to $1 million if more than 3.35% of the loans originally in the bond went bad. So far, the wager hasn't made money.

Meanwhile, data on loan delinquencies suggest that lending standards have indeed fallen. As of August, about 3% of borrowers who took out subprime loans in 2006 were more than 60 days behind on their payments -- about three times the level two years earlier.

The annual cost of $1 million in insurance against moderately risky subprime-backed bonds has gone from a low of about $21,500 in early August to $25,000 Friday, and has spiked as high as $27,800. Market participants say big hedge funds increasingly are using the derivatives to make outright bets against U.S. homeowners.
This summer, for example, New York hedge-fund manager Paulson & Co. launched a fund that has aimed specifically at profiting on subprime defaults.

III. THIS WAS SOMEWHERE IN BETWEEN ...


Lehman Bros goes bankrupt, Merrill Lynch is bought up... Mortgage giants Fannie Mae and Freddie Mac are taken over by the government. Bear Stearns collapses, America's largest insurance company AIG's share collapse from $22.19 on September 9 2008, to less than $4.00 at the close of trading on September 16, a decline of more than 80 percent of its value.


A.I.G. Lists Banks It Paid With U.S. Bailout Funds
American International Group on Sunday released the names of dozens of financial institutions that benefited from the Federal Reserve’s decision last fall to save the giant insurer from collapse with a huge rescue loan.

Financial companies that received multibillion-dollar payments owed by A.I.G. include Goldman Sachs ($12.9 billion), Merrill Lynch ($6.8 billion), Bank of America ($5.2 billion), Citigroup ($2.3 billion) and Wachovia ($1.5 billion).

Big foreign banks also received large sums from the rescue, including Société Générale of France and Deutsche Bank of Germany, which each received nearly $12 billion; Barclays of Britain ($8.5 billion); and UBS of Switzerland ($5 billion).

Ever since the insurer’s rescue began, with the Fed’s $85 billion emergency loan last fall, there have been demands for a full public accounting of how the money was used. The taxpayer assistance has now grown to $170 billion, and the government owns nearly 80 percent of the company.
Goldman converted to a bank holding company during the crisis, allowing it to receive $10 billion in federal bailout money.


IV. AND THIS IS THE MORAL HAZARD OF THAT STORY ...

The Natural Result of Deregulation
If the allegations against Goldman Sachs are true, then much of the blame for investors’ losses in the Abacus deal can be laid at the feet of an obscure statute passed by Congress in 2000, the “Commodities Futures Modernization Act.”

In one dramatic move, that act eliminated a longstanding legal rule that deemed derivatives bets made outside regulated exchanges to be legally enforceable only if one of the parties to the bet was hedging against a pre-existing risk.

This traditional derivatives rule against purely speculative derivatives trading has a parallel in insurance law, because insurance, like derivatives trading, is really just a form of betting. A homeowner’s fire insurance policy, for example, is a bet with an insurance company that your house will burn down.

Under the rules of insurance law, you can only buy fire insurance on a house if you actually own the house in question. Similarly, under the traditional legal rules regulating derivatives trading, the only parties who could use off-exchange derivatives to bet against the Abacus deal would be parties who actually held investments in Abacus.

If we allow the unscrupulous to buy fire insurance on other people’s houses, the incidence of arson would rise sharply.

Labels: , ,